03.1
Conventional
The straightforward one. Strong credit, steady income, the best pricing on the board.
From 3% down · Most common
Kansas & Missouri · Twenty years of home loans
Beau Bryan has written home loans in Kansas and Missouri for twenty years — and you’ll see how every piece works before you sign anything.
NMLS #732702 · New American Funding · Overland Park, KS
Pre-approval, rate lock, underwriting, closing day — every step handled, explained, and on time.
So the only thing on your mind is the front door.
Fig. 02 · The lender
Beau Bryan is the Branch Manager at New American Funding in Overland Park, Kansas. He has spent more than twenty years in mortgage lending — through refi booms, a crash, and the strangest markets on record. Rate, payment, closing costs, timeline: he gives you real numbers and tells you plainly which loan fits and why.
Branch Manager · Overland Park, KSNMLS #732702
Fig. 03 · The programs
Beau prices all four side by side before recommending one — so the loan fits you, not the other way around.
The straightforward one. Strong credit, steady income, the best pricing on the board.
From 3% down · Most common
The forgiving one. A lower step in the door — the way most first-time buyers actually get in.
3.5% down · Flexible credit
The earned one. Zero down for veterans and active duty — Beau treats it like the benefit it is.
0% down · Service earned
The flexible one. Self-employed, 1099, real income that doesn’t fit a W-2 box — there’s still a loan for that.
Bank statements OK · Self-employed
Fig. 03 Program elevations — same house, four doors in
Fig. 04 · The monthly payment
The part that buys the house. Every month, a little more of it is yours.
The cost of borrowing. Beau shows you rate and APR side by side, before you commit to anything.
Collected monthly, held in escrow, paid for you. On the sheet from day one — never a surprise at closing.
Only if you put less than 20% down — and on most conventional loans it comes off at 20% equity. Beau tracks the date so you stop paying the month you can.
Fig. 04 Payment anatomy — it traces itself; tap a part to hold it
Fig. 05 · The estimator
Same four parts as above — now with your price, your down payment, your rate. Nothing is submitted. Nothing is stored. Move the sliders and watch the payment move.
Estimated monthly payment
$2,869/mo
$346,500 borrowed over 30 years at 6.500%.
Interest paid over the full term$442,616
A 15-year term costs $734 more a month — and $268,914 less in interest.
Principal and interest are the first payment’s split — principal grows every month after. Taxes and insurance estimated at 1.30% and 0.35% of price per year (Johnson County range). Mortgage insurance applied at 0.52% per year when the down payment is under 20%. Estimate only — not a quote, a rate offer, or a commitment to lend. Beau prices the real thing in about ten minutes.
Fig. 05 Working estimate — the same four parts, solved for your inputs
Fig. 06 · The range
Most people only ever hear about two loans. There are a lot more than two — and three of them decide more Kansas City deals than the rest put together.
New American Funding puts up to $6,000 toward the down payment in eligible areas — and eligibility is drawn by census tract, not by income alone. Beau checks the address before you ever fill anything out.
Up to $6,000 · Eligible areas
Make a cash-backed offer on the new house first, then sell the old one without a contingency hanging over the deal. In a multiple-offer weekend, that is usually the whole difference.
Buy before you sell · No contingency
Qualify on 12 or 24 months of deposits instead of a tax return written to minimize income. If you own the business, this is often the difference between “declined” and “approved.”
12 or 24 months · Self-employed
Fig. 06 Program index — licensed in Kansas and Missouri · NMLS #732702
Fig. 07 · The process
No portal maze, no mystery underwriter. One person, three steps, real numbers at every one.
Step 01
Call the direct line. Ten minutes, no phone tree, no application first — just what you’re trying to do.
Step 02
He prices it across Conventional, FHA, VA and Non-QM — rate, payment, and closing costs on paper, side by side.
Step 03
Clear to close — with the same person answering the phone the whole way through.
Fig. 07 Sequence — call, math, keys
Fig. 08 · The file
One file, thirty days, one number. Drag the timeline — on a file Beau runs, day 30 closes on the figure day 1 quoted, while the typical lender’s number quietly drifts up.
Loan estimateDay 1
Monthly payment
$2,847/moRate locked · 6.500%
Fig. 08 Sample file — drag the timeline; illustrative figures, not an offer of credit
Fig. 09 · On camera
The same plain talk you get on the phone — recorded, so you can check the answers before you ever call.
Fig. 09 Recorded answers — tap any plate; it plays right here
Fig. 10 · The reviews
Twenty years of clients, one recurring theme: he picks up, he explains, nothing gets hidden.
Beau walked us through every number before we signed anything. First house, zero surprises.
First-time buyers · Overland Park, KS
He answered his own phone on a Saturday and had our rate locked by Monday morning.
Refinance · Lee’s Summit, MO
Three lenders told us no. Beau found the loan that actually fit how we get paid.
Self-employed purchase · Olathe, KS
Fig. 10 Sample copy shown — Beau’s live Google reviews drop in here
Twenty years of straight answers. One phone number.
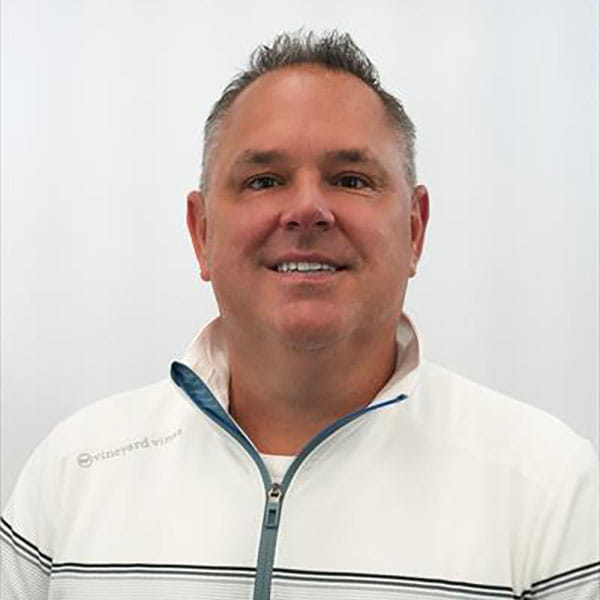
Beau Bryan
Branch Manager
NMLS #732702 · New American Funding · Overland Park, KS